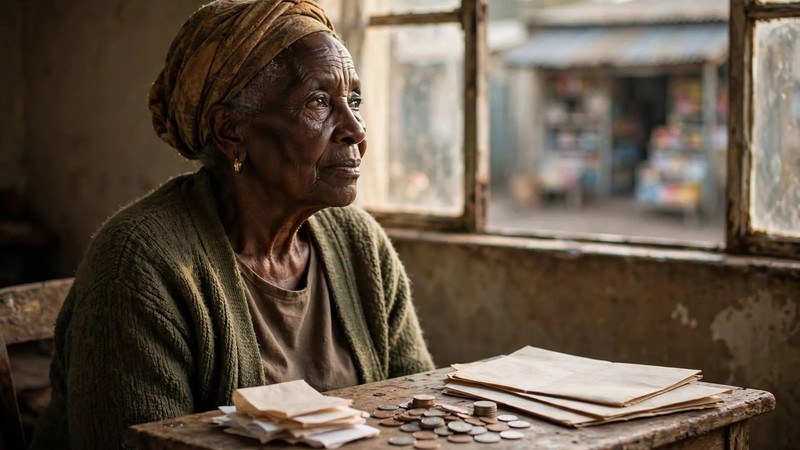
Earlier this week, while scrolling through TikTok, I came across a video of an elderly woman from Mdantsane in the Eastern Cape who had apparently been caught taking food from a shop without paying. My immediate reaction was to laugh, perhaps because of how the incident was presented, or because social media has gradually conditioned us to consume even the most uncomfortable moments of human experience as entertainment.
But later, as I sat reflecting on what I had watched, the laughter disappeared, replaced by a question that has continued to trouble me: what has happened to us as a society when the sight of an elderly woman apparently taking food becomes something to laugh about before it becomes something to worry about?
I do not know that woman’s circumstances, whether the allegations were accurate, or what motivated her actions. It would be irresponsible to invent an explanation. Yet the incident made me think about the financial pressures facing ordinary South Africans, particularly elderly people whose limited incomes must stretch across competing responsibilities.
It also made me think about funeral insurance.
In South Africa, preparing for death is more than a financial decision. It is deeply connected to culture, family responsibility and the dignity with which we wish to bury those we love. Funeral cover has therefore become an important product, sold through insurers, banks, retailers, funeral parlours and other distribution channels, each promising some measure of financial protection when families are at their most vulnerable.
There is nothing inherently wrong with this. Funeral insurance provides an essential service, particularly where the cost of burial could otherwise overwhelm an entire family. But somewhere between the legitimate need for protection and the commercial pursuit of policy sales, an uncomfortable question has emerged.
Have we become so efficient at helping people prepare for death that we have forgotten to ask whether they can afford to live?
Consider a pensioner receiving a modest monthly income who has accumulated several funeral policies over the years, perhaps purchasing one through a retailer, another through a funeral parlour, a third through an insurer and an additional policy after being persuaded that existing cover might not be sufficient. Each policy may have appeared affordable when purchased. Each provider may have fulfilled its disclosure obligations. Yet nobody may have helped that pensioner understand the cumulative financial consequences of those individual decisions.
One policy costs R120 monthly, another R180, a third R150 and a fourth R200. Individually, these amounts appear manageable, but collectively they consume R650 every month, or R7,800 annually, before the household has purchased bread, electricity, medication or transport.
These figures are illustrative, but the question they raise is fundamental: who is looking at the consumer’s total financial exposure when every provider sees only the product it has sold?
The insurer knows its policy. The retailer knows the product distributed through its channel. The funeral parlour knows its arrangement. The bank processes the debit orders. Yet the consumer, whose money sustains the entire system, may be the only participant without a complete picture of what has been purchased.
Here lies a structural weakness that deserves far greater attention.
South Africa has made financial products increasingly accessible, but accessibility does not automatically translate into financial wellbeing. A consumer can own several policies without knowing whether the benefits overlap, whether the same family members are covered repeatedly, which waiting periods apply, or whether the combined premiums remain affordable.
More importantly, the consequences of these decisions may remain invisible because every debit order appears relatively small, every policy carries the reassuring language of protection, and every monthly payment reinforces the belief that the family is becoming more secure.
Until the money runs out. Until the pension arrives and the debit orders begin. Until the person who has spent years preparing financially for death discovers that there is barely enough money left for the necessities of life.
What kind of financial protection leaves a person financially vulnerable while they are still alive?
This is not an argument that funeral insurance causes poverty, nor am I suggesting that the elderly woman in Mdantsane had funeral policies or that insurance premiums contributed to her circumstances. Her experience simply prompted a broader reflection about financial vulnerability and the difficult choices confronting households with limited resources.
The concern is that our understanding of financial inclusion remains too heavily focused on product ownership rather than consumer outcomes. We celebrate when more people purchase insurance, open bank accounts and enter the formal financial system, but seldom ask whether the financial commitments accumulated through that participation are improving their lives.
A person can be financially included and financially distressed at the same time. This contradiction should concern regulators, insurers, retailers and everyone involved in consumer protection, because a financial system cannot claim meaningful success merely because it has expanded access while leaving some consumers unable to understand the combined consequences of their financial commitments.
There is an opportunity to change this.
Imagine a South Africa where consumers could access a secure digital platform that, with their informed consent and appropriate safeguards, brings together funeral policy information from participating providers, showing premiums, benefits, insured family members, waiting periods and possible areas of overlapping cover.
Imagine a pensioner being able to understand, perhaps for the first time, exactly how much of their monthly income is committed to funeral insurance, which policies provide distinct benefits, and which arrangements deserve further review.
Imagine financial advisers assessing existing cover before recommending additional products, insurers receiving fewer avoidable complaints arising from misunderstanding, and regulators gaining access to anonymised information that helps identify patterns of consumer vulnerability.
Such a platform would not automatically determine that multiple policies are unnecessary, because different policies may serve legitimate purposes, and cancelling cover without understanding the consequences could leave families exposed. It would instead give consumers the information needed to make better decisions.
I am currently developing a digital platform around this challenge, convinced that the next frontier of financial inclusion is not simply giving people access to more products, but enabling them to understand and manage what they already own.
Achieving this would require cooperation between insurers, regulators, retailers and technology providers, supported by lawful data sharing, independent governance and strong consumer privacy protections. It would also require a shift in how we measure success.
Instead of asking only how many policies were sold, we should ask how many consumers understand their cover, how many avoid unnecessary financial commitments, and how many families can approach a funeral without discovering that the protection they believed they had is different from what their policies actually provide.
There is a deeper governance lesson here.
Institutions can comply with their individual obligations while the collective experience of the consumer remains deeply problematic. A policy can be properly sold, a debit order lawfully processed, and a disclosure document correctly issued, yet the household may still be carrying financial commitments it does not fully understand. Compliance by individual institutions does not necessarily produce protection for the consumer navigating the system.
Perhaps this is where our understanding of responsible financial services must evolve: from merely ensuring that products are lawfully sold towards ensuring that consumers can understand their combined financial commitments and make informed choices.
I keep returning to that elderly woman in Mdantsane.
I do not know her story, and I refuse to turn her circumstances into evidence for an argument they cannot support. But I know that my initial laughter now troubles me, because it reminds me how easily we become spectators to another person’s possible humiliation without considering the wider vulnerabilities that exist in our communities.
Perhaps the real question is not simply why an elderly woman might take food from a shop, but whether we have become sufficiently attentive to the financial pressures that can undermine dignity long before a person reaches such a moment.
We should never accept a society in which financial protection becomes another source of financial anxiety.
A country should not become so efficient at collecting premiums for tomorrow’s funeral that it forgets the importance of today’s bread.
Because dignity should not begin when someone dies.
It should begin while they are still alive.
Nyaniso Qwesha is a governance, risk and business professional, author and public commentator. His work examines governance, institutional accountability, public sector performance and corporate leadership.
The views expressed do not necessarily reflect those of IOL


